LB AI-Native Neighborhood Program · Midwest Pilot
The Offer, in One Page.
SoHo Apartments · Deal Terms
A trophy asset with a defined exit and a first look at a 10-year program. Investors who come in on SoHo receive scheduled buybacks and priority access to Fund 1.
The Program At A Glance
11
Buildings
5
Funds
10 yrs
Horizon
~$900M to $1B
End Portfolio
~$404M
LP Raise Total
~$45M/yr
End Cash Flow
What You Are Investing In
Not a deal. A program, beginning with a deal.
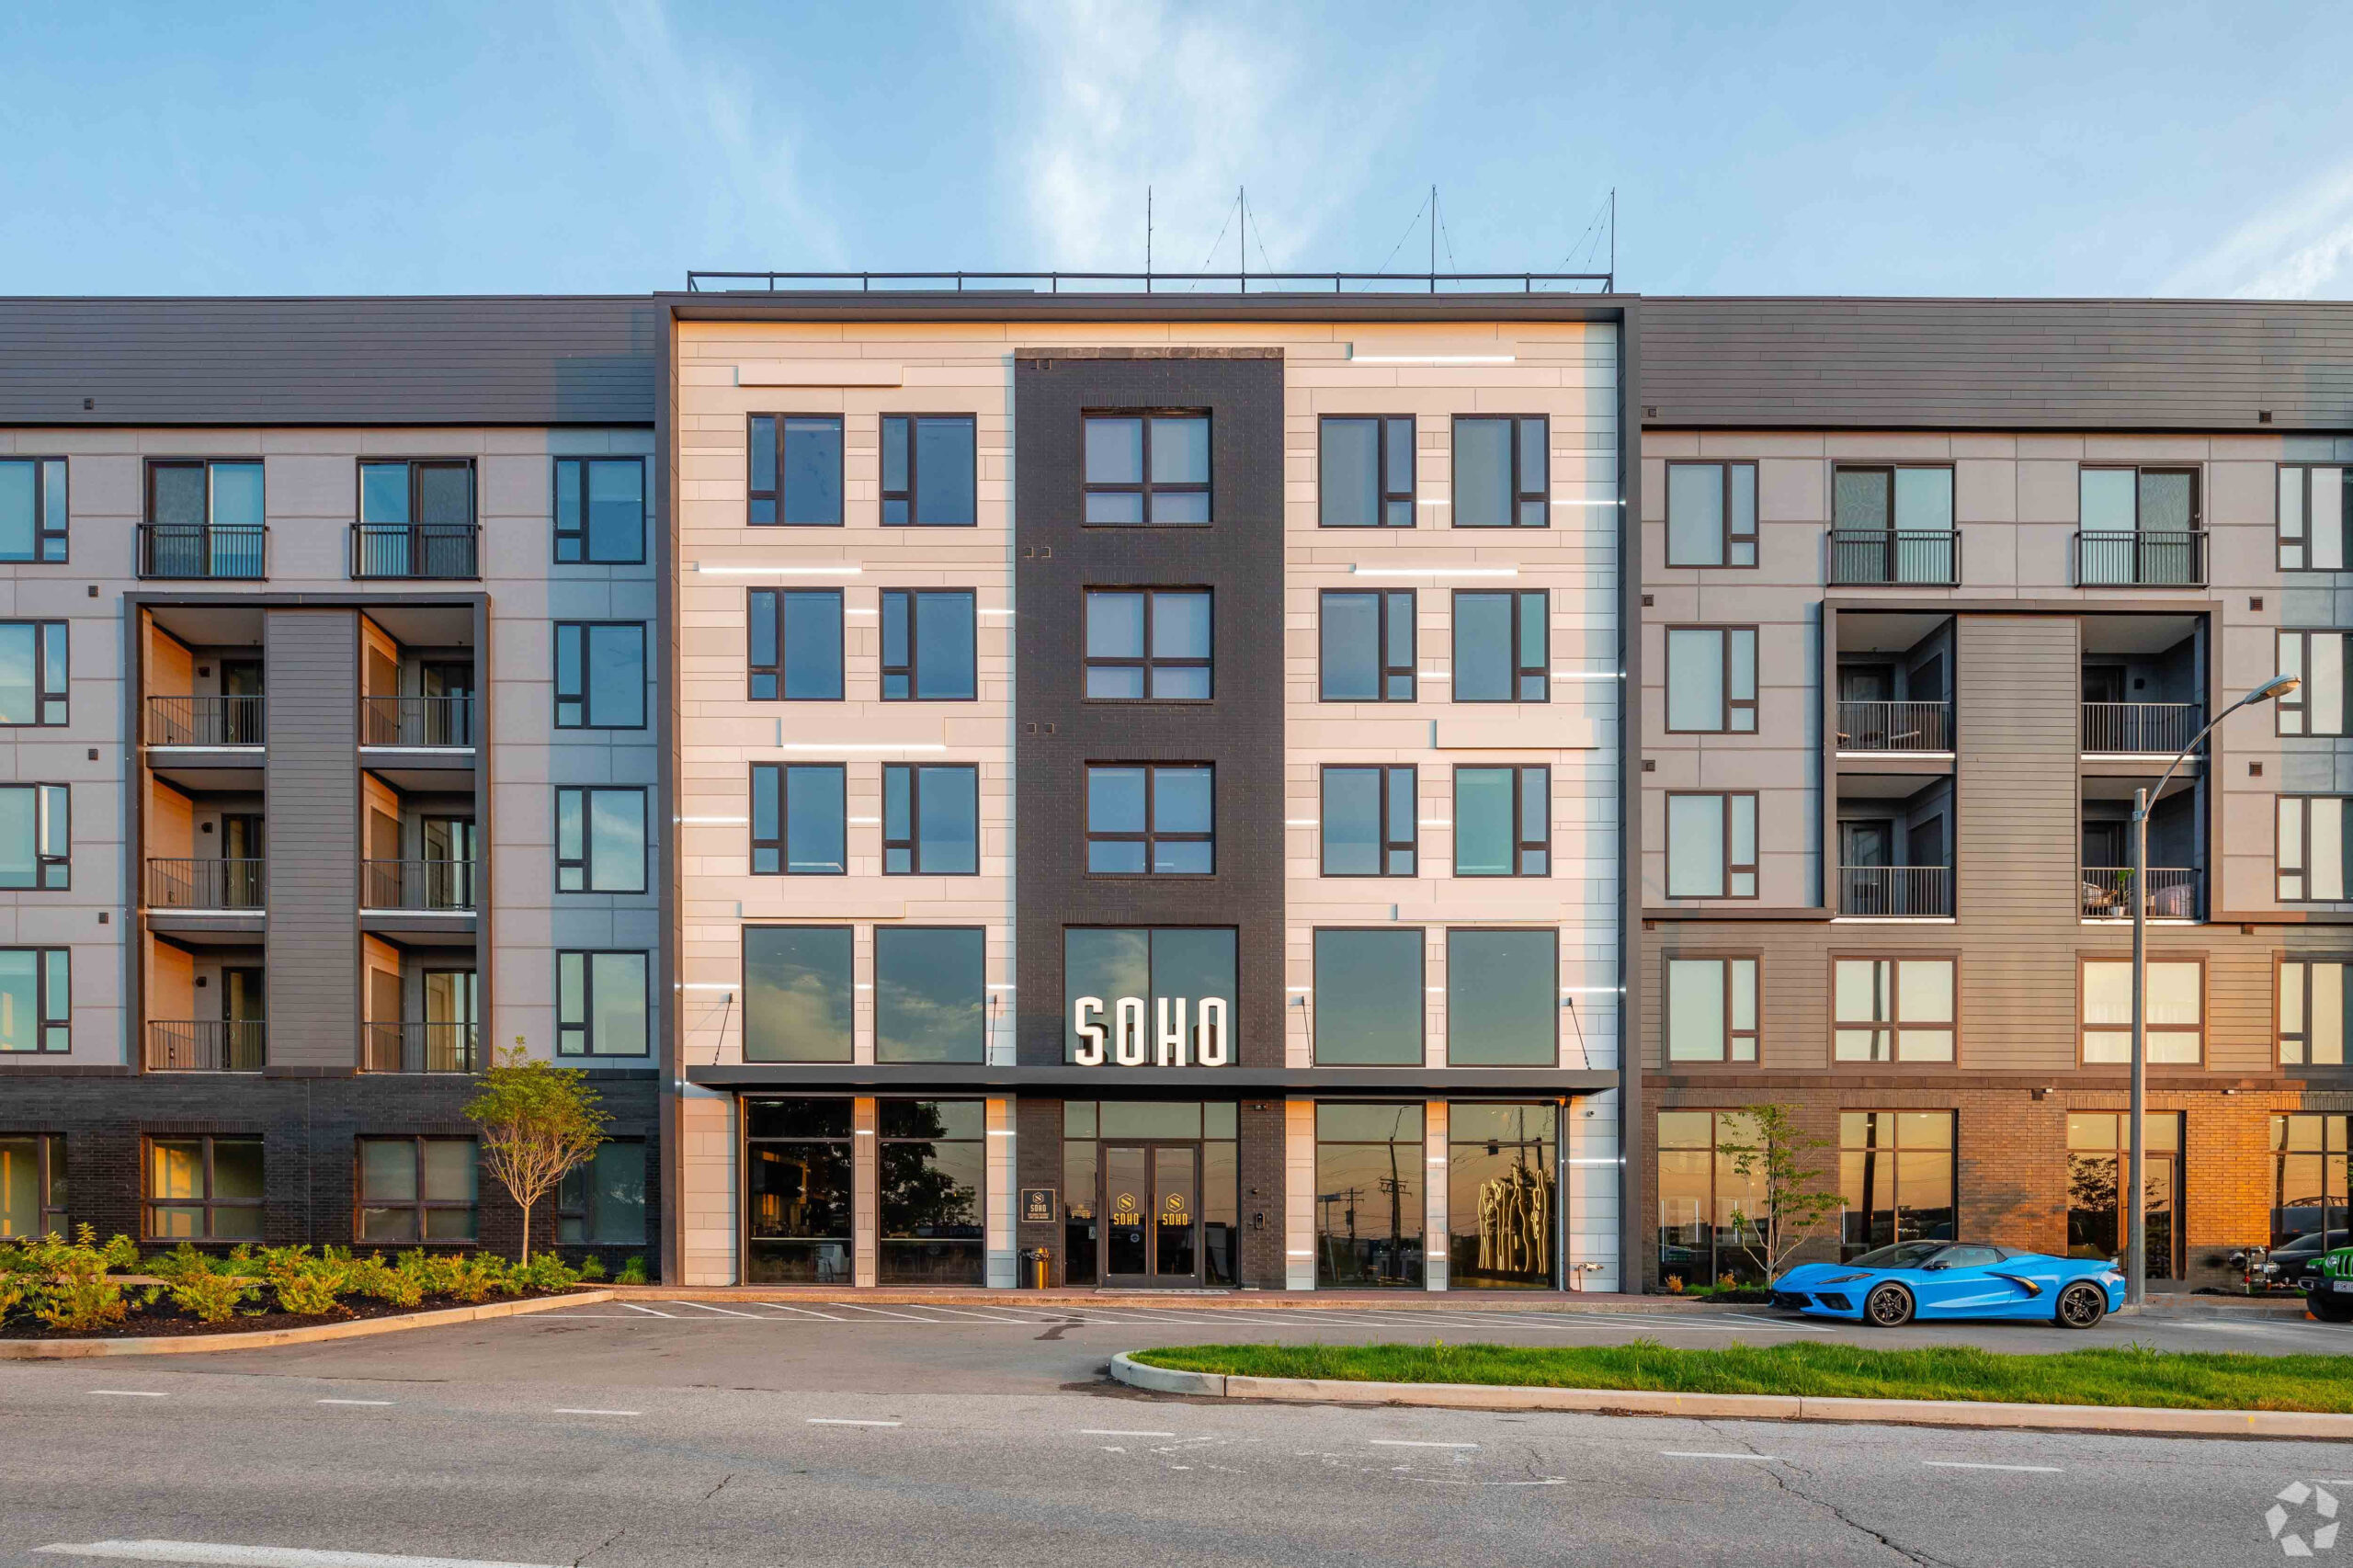
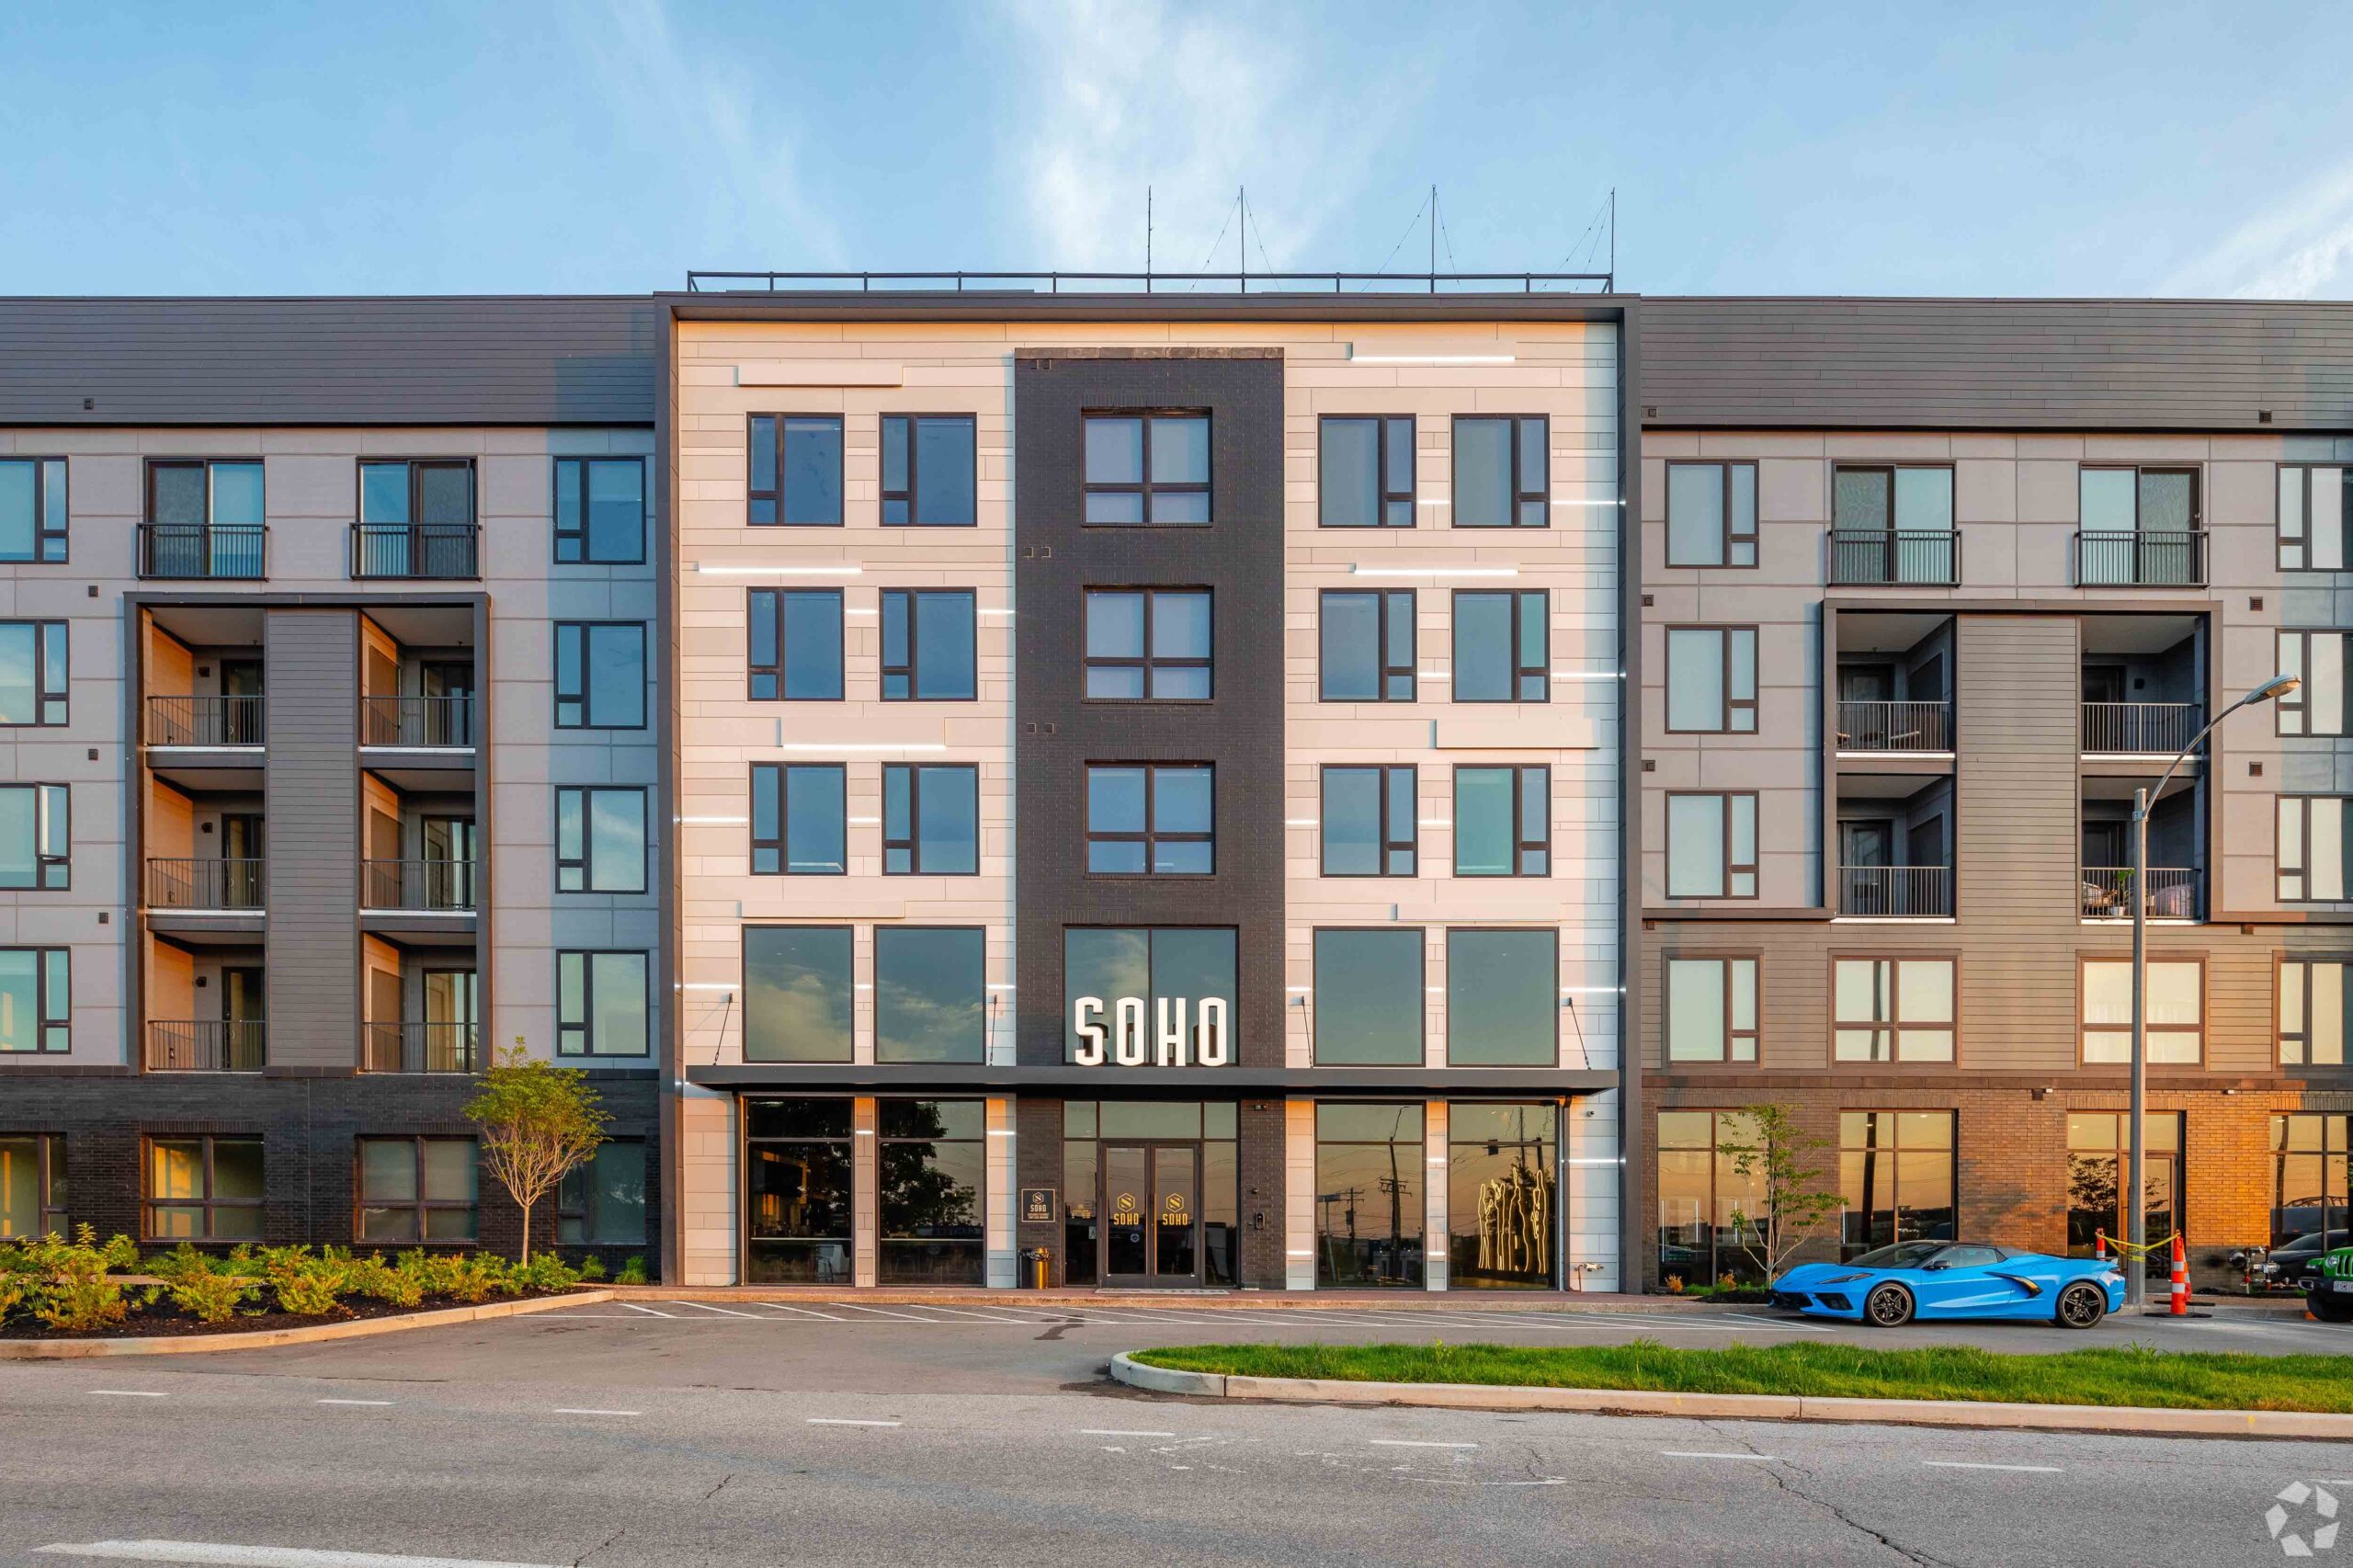
SoHo is a stabilized 322-unit Class A asset in Soulard, one of the strongest submarkets in St. Louis, acquired below replacement cost due to a forced seller disposition. It is cash flowing from the day investors close. It is the proof-of-concept for the larger LB AI-Native Neighborhood Program.
LP capital returns on a defined schedule with progressive tranche buybacks from Year 3 through Year 7 at a blended 2.09x MOIC and approximately 14% IRR. Every LP exits on schedule. No open-ended hold. No vague timing risk. No promote. No acquisition fee. No asset management fee. No disposition fee. Just the return schedule and the right to participate in Fund 1 when it launches.
322
Units
2021
Year Built
$75.0M
Purchase Price
$232,919
Price / Unit
12%
Target IRR
1.85x
Equity Multiple
Why This Asset
322 Class A units. Stabilized. Below replacement cost.
Forced disposition due to federal fraud charges against the developer. LuxLiving is systematically liquidating its St. Louis portfolio, creating a rare opportunity to acquire a trophy Class A asset below replacement cost with motivated seller pricing.
The result: a $75.0M acquisition at $232,919 per door. Roughly 33% below replacement cost in a supply-constrained submarket. The seller needs out. We underwrite the asset. The math is the pitch.
The Buyback
Defined exits on a scheduled path.
LB AI is contractually obligated to buy out LP positions on this schedule. A one-time 12-month extension option exists if capital markets tighten, with a 0.15x MOIC extension fee paid to affected LPs. Failure to execute after extension triggers a forced asset sale at the greater of appraised FMV or the scheduled MOIC. LPs are protected at every step.
| Tranche | Year | MOIC | % of LP | Implied IRR |
|---|---|---|---|---|
Tranche 1 | Year 3 | 1.60x | 15% | ~17% |
Tranche 2 | Year 4 | 1.85x | 20% | ~16% |
Tranche 3 | Year 5 | 2.10x | 25% | ~16% |
Tranche 4 | Year 6 | 2.30x | 20% | ~14% |
Balloon Greater of 2.50x or appraised FMV | Year 7 | 2.50x | 20% | ~14% |
Blended Weighted Across all tranches | 2.09x | 100% | ~14% | |
The LB AI Side
10% equity. 10% revenue share. All tech. No fees.
Light Brands AI receives a 10% equity position in the LLC as sweat equity for contributing the technology stack, operational oversight, and acquisition pipeline. LB's 10% equity is subordinated to the LP 7% preferred return. LPs are paid first.
A 10% revenue share funds LB AI's operating budget (tech team, investor relations, acquisitions) and feeds the LB treasury that fuels the progressive buyback. This revenue share replaces the typical acquisition fee, asset management fee, disposition fee, and promote that most syndications stack. LPs get more of the waterfall as a result.
LB's upside comes from the 10% equity growing into 100% ownership through the scheduled buyback. LP upside comes from the defined return schedule. Aligned incentives. No hidden fees.
The 10-Year Arc
LB AI-Native Neighborhood Program: Midwest Pilot
SoHo Pilot
Year 0 to Year 1Proof-of-concept, St. Louis
Active
Fund 1 Launch
Year 1St. Louis cluster, 2 properties
Scheduled
Fund 2 Launch
Year 2St. Louis + first expansion
Scheduled
Fund 3 Launch
Year 3Midwest expansion cluster
Scheduled
Fund 4 Launch
Year 4Midwest consolidation
Scheduled
Fund 5 Launch
Year 5Pick-the-winners cluster
Scheduled
Rolling Acceleration
Year 3 to Year 10Progressive LP buyback across all funds
Ongoing
Program Complete
Year 1011 buildings owned outright, $45M+/yr free cash flow
Target
The Capital Stack
How the $75M deal becomes a $28.9M LP raise.
SoHo is a $75M acquisition. Senior debt covers the majority, closing costs sit on top, and LPs fund the equity slice. The LP raise is what you are writing a check into, not the full purchase price.
Purchase Price
$75.0M
The total acquisition cost of SoHo Apartments at $232,919 per door. This is the deal, not the check.
Senior Debt (65% LTV)
$48.8M
Fixed-rate agency loan amortizing over 30 years with an initial interest-only period. Lenders fund this piece, not LPs.
LP Equity Raise
$28.9M
The equity slice LPs fund. This is the number that maps to your check size below. Closing costs are included.
$75.0M purchase = $48.8M senior debt + $28.9M LP equity raise (includes ~$2.6M closing costs)
How The Financing Closes
Debt and equity are arranged in parallel, not in sequence. The senior lender and the LP equity close on the same day, simultaneously. On closing day, the lender wires the $48.8M loan, escrow releases the $28.9M in LP equity, and the building transfers into the fund LLC.
The senior loan is secured by the building itself. The lender holds a mortgage lien on SoHo, which means the building backs the debt. LPs are not personally liable for the loan. It is non-recourse at the individual investor level.
We use debt for three reasons: it is cheaper than equity (~5.5% vs ~14% target IRR), the interest is tax-deductible, and leverage converts moderate property returns into strong equity returns. Paying for most of the building with 5.5% money while targeting 14% on the equity slice is the entire mechanism that makes the deal work.
The Decision
Two ways to participate.
The LP equity raise is $28.9M. That raise can be funded by one investor or split across a syndicate. Both paths receive the same deal economics and the same buyback schedule.
Path One
The Whole Thing
One $28.9M check
A single LP or family office writes the full $28.9M equity raise and owns the entire LP position in SoHo. The building costs $75.0M to acquire; $48.8M is covered by senior debt; the remaining $28.9M is the LP check.
- • Full control of the LP position
- • First call on Fund 1 allocation when it launches
- • Custom reporting and governance rights
- • Direct relationship with the LB AI principals
Path Two
The Syndicate
$100,000 minimum per LP
A group of accredited investors splits the $28.9M equity raise across individual commitments. Minimum check per LP is $100,000. Standard Reg D 506(b) structure with pro-rata distributions.
- • $100,000 minimum commitment per LP
- • Pro-rata share of all tranche buybacks
- • Priority access to Fund 1 allocation
- • Quarterly distributions and reporting
The Market Context
The supply faucet is turning off.
Construction starts dropped 74% from the 2021 peak. The multifamily pipeline is collapsing nationally.
Roughly 270,000 completions expected in 2026 — the slowest year in a decade.
National vacancy projected at 4.9% by end of 2025.
The 2021 supply wave crests in 2025. The back half of this decade structurally favors existing stabilized assets in markets with low pipeline risk, because new construction cannot ramp fast enough to satisfy the demand baseline.
Why St. Louis
Undervalued anchor for the Midwest Pilot.
The St. Louis metro has one of the lowest structural vacancy rates in the country, driven by a stabilized labor base and limited new construction.
Class A price per unit runs 40 to 60% below Sun Belt peers for equivalent or better fundamentals.
Property taxes and insurance are both materially lower than coastal alternatives, protecting NOI.
The National Geospatial-Intelligence Agency (NGA) is building a $1.75B campus in North St. Louis, bringing 3,150 high-wage federal jobs to the metro.
Reg D 506(b) · Accredited Investors